Affluent banking is a stack, not a lounge photo
Malaysians who start looking at affluent banking often begin with the wrong artefact: a brochure of airport lounges, a gold bar on velvet, or a home-financing rate table printed in bold. Those artefacts matter later. First you need a clear stack: how day-to-day banking is supported, how surplus cash might sit in precious metal, and how a house purchase would be financed under an Islamic contract if that is your preference.
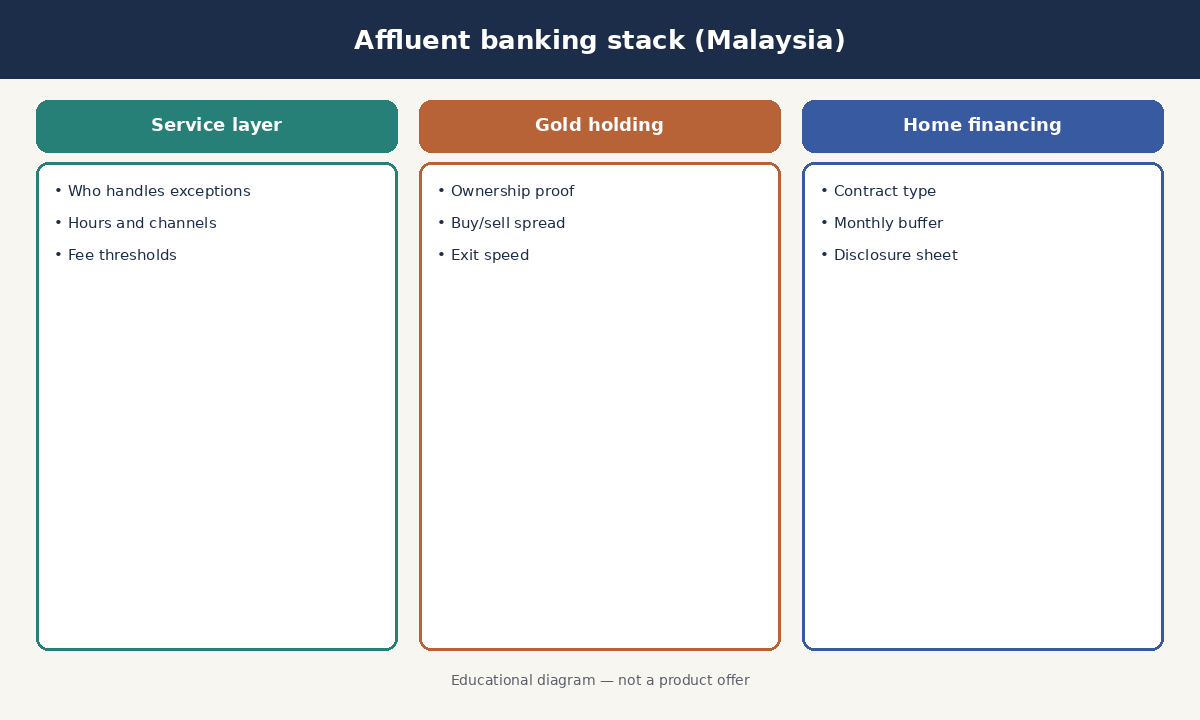
Three lanes on one sheet. Answer your own questions before you argue with a relationship manager.
What “affluent” usually changes in practice
Affluent banking is not a personality label. It is a service layer: who you call when a transfer fails, how exceptions are handled, whether wealth and financing conversations sit with the same team, and which fees are waived only if balances stay above a threshold. Write those operational needs first. Travel weeks, multi-currency inflows, and family account structures create different pain points than a simple salary account.
When you scan public hubs that describe Al Rajhi Affluent, treat them like catalogues. Note relationship coverage hours, digital versus branch mix, and how product disclosure sheets are shared. Ignore lifestyle photography. A practical shortlist compares exception handling and fee clarity, not lounge photography.
Islamic affluent banking context in Malaysia also means asking how Shariah-compliant products are supervised and disclosed. Bank Negara’s Islamic finance framework sits behind licensed Islamic banks; your job as a customer is still to read the Product Disclosure Sheet for each facility, not to assume brand language equals contract detail.
Gold as a surplus holding, not a personality
Bank gold investment products attract people who want metal exposure without storing physical bars at home. The useful questions are boring: is ownership physical or constructive, how is allocation evidenced, what buy and sell spreads apply, and how quickly can you exit. Gold can sit beside cash for surplus you do not need next month. It is a poor substitute for emergency liquidity if spreads and delays are material.
Compare a bank bank gold investment pages page against a jewellery shop quote using the same purity and weight language. Ask for storage and ownership proof in writing. If you care about Shariah parameters, look for allocated gold and spot settlement language consistent with industry standards such as AAOIFI’s gold standard, and confirm the specific product’s Shariah notes rather than assuming the word “Islamic” covers every mechanic.
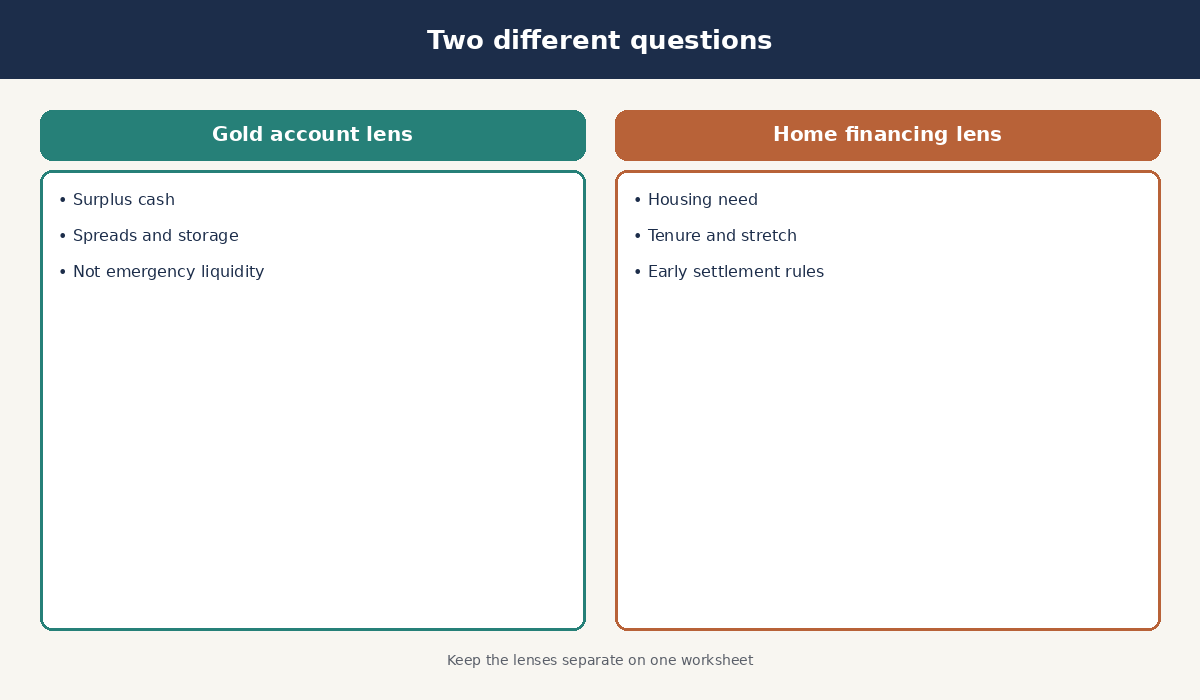
Gold answers a surplus question. Home financing answers a housing question. Mixing the two into one emotional decision usually muddies both.
Islamic home financing: read the contract type
Home financing under Islamic banking uses trade, lease, or partnership-style contracts rather than a conventional interest loan label. That does not remove the need to understand monthly stretch, tenure, early settlement costs, and what happens if income dips. Ask which contract type applies, how profit rates are reviewed, and which documents the bank needs before offer.
Public pages that outline Islamic home financing help you scan features side by side. Bring your own numbers: take-home pay, existing commitments, and a buffer for rates that can reprice. Bank Negara’s consumer guides on home financing stress reading disclosure sheets and understanding your obligations before you sign; that habit beats chasing a headline rate.
If you want a neutral primer on how mortgage-style housing finance works in cash-flow terms (principal, interest or profit, and long tenure), Khan Academy’s introduction to mortgage loans is a clean educational walkthrough before you sit with any bank:
Related watch: Khan Academy explains mortgage loan mechanics in plain language, useful before you compare Islamic home financing disclosure sheets.
Read protections before comparing products
Eligible deposits at member banks sit under Malaysia’s deposit insurance system. PIDM deposit protection covers eligible deposits up to the stated limit per depositor per member bank, with separate treatment for conventional and Islamic deposits. Confirm each product’s eligibility. Cover does not protect investment losses on gold price moves or poor housing choices.
For housing finance literacy, Bank Negara’s consumer materials on Islamic banking consumer primers remain a stable map. Pair that with the Bank’s product transparency and disclosure rules so every shortlisted fee, rate, and obligation is readable on a disclosure sheet.
This month, keep the pass small. Map one service-layer need for affluent banking, price one gold exit scenario including spread, and draft a housing cash-flow buffer before you collect rate quotes. Affluent banking in Malaysia works better when the stack leads and the lounge photo follows.