Men’s Multivitamins in Malaysia: Labels, Limits and Realistic Expectations

Men’s Multivitamins in Malaysia: Labels, Limits and Realistic Expectations
Open hand holding two beige herbal supplement capsules against a lilac background

What a men’s multivitamin can reasonably cover

A men’s multivitamin is often sold as a daily safety net. For people who already eat a varied diet, the net may catch less than the label suggests. The useful question is narrower: which nutrients are you actually short on, and is a broad tablet the right way to fill them? Product pages for a men’s multivitamin formula can show typical ingredient lists, but they cannot replace a look at your own meals, bloodwork or pharmacist advice.

The US Office of Dietary Supplements summarises the evidence in plain language on its multivitamin/mineral consumer fact sheet. Routine multivitamins do not reliably prevent heart disease or cancer in well-nourished adults. They can still help when diet is restricted, appetite is poor, or a clinician has flagged a gap. That distinction matters in Malaysia too, where marketing language travels faster than lab results.

Think of the bottle as a tool for coverage, not as proof that yesterday’s meals failed. If breakfast is toast and coffee, lunch is a rushed rice plate, and dinner is late takeaway, food fixes will usually move the needle more than another tablet. If you already rotate vegetables, eggs, fish, legumes and dairy or fortified alternatives, a multivitamin is more of a hedge than a foundation.
Open hand holding two beige herbal supplement capsules against a lilac background
Capsules look alike in the hand; only the label shows the nutrient forms, doses and what is missing.

How to read the label without getting lost

Check the serving size first. Some bottles need two tablets to hit the amounts on the panel. Then scan iron content: many men’s formulas keep iron low or omit it because adult men rarely need extra iron unless a doctor says otherwise. Look at vitamin A form, folate versus folic acid labelling, and whether vitamin D and B12 sit near useful daily amounts rather than token dustings.

Upper limits matter when you already take separate supplements. Stacking a multivitamin with high-dose singles can push some nutrients higher than intended. The NHS vitamins and minerals overview is a calm reference for what food already supplies and where supplements are usually discussed. Keep a simple notebook of everything you swallow, including powder drinks marketed as “daily complete” mixes.

Also notice fillers and proprietary blends that hide exact milligram amounts behind a single line. Transparency is not a guarantee of quality, but opacity makes comparison harder. If two products claim similar benefits and only one shows clear amounts, prefer the one you can actually evaluate.

A nutritionist walks through when a multivitamin helps and when food is enough.

Milk thistle and gut supplements sit in a different drawer

People often bundle liver support and probiotic products into the same shopping trip as a multivitamin. That mix can make sense as a personal routine, but the evidence and the job of each product are not the same. Milk thistle extracts are studied for specific liver-related contexts, not as a general energy booster. A product note such as a milk thistle supplement page should be read as ingredient information, not as a diagnosis tool.

Probiotics are strain-specific. A guide on choosing a probiotic for digestive health is only helpful if you match the strain and storage needs to the symptom you actually have. Bloating after antibiotics is a different problem from long-running IBS, and neither is fixed by adding random colony counts. Heat-sensitive strains also fail quietly if the bottle sat in a warm delivery van for hours.
Carrots, spinach, tomatoes, raspberries and walnuts laid out on a white surface
Food still does most of the micronutrient work for people who can eat a varied plate.

When to involve a pharmacist or doctor

Bring the bottle if you take blood thinners, thyroid medicine, or treatment for chronic disease. Some nutrients and herbal extracts interact with medicines. Unexplained fatigue, unexplained weight loss, or neurological symptoms need assessment, not a stronger multivitamin. The same applies if you have had bariatric surgery or a diagnosed malabsorption issue; those situations usually need a clinician-led plan rather than aisle browsing.

If blood tests already show a deficiency, targeted replacement is usually clearer than a broad multivitamin. If tests are normal and meals are decent, spending the same money on food variety is often the quieter win. Ask for copies of results so you can track changes over months instead of guessing from energy levels alone.

A practical monthly check

Once a month, line up every supplement you take and ask three questions: why did I start this, what would tell me it is working, and what would make me stop. Cross out anything that exists only because of a one-time sale. Keep what still answers a real gap. That habit matters more than chasing a perfect men’s formula, and it keeps your cabinet from becoming a museum of unfinished bottles.
Malaysia Guide to Affluent Banking and Gold Accounts

Malaysia Guide to Affluent Banking and Gold Accounts
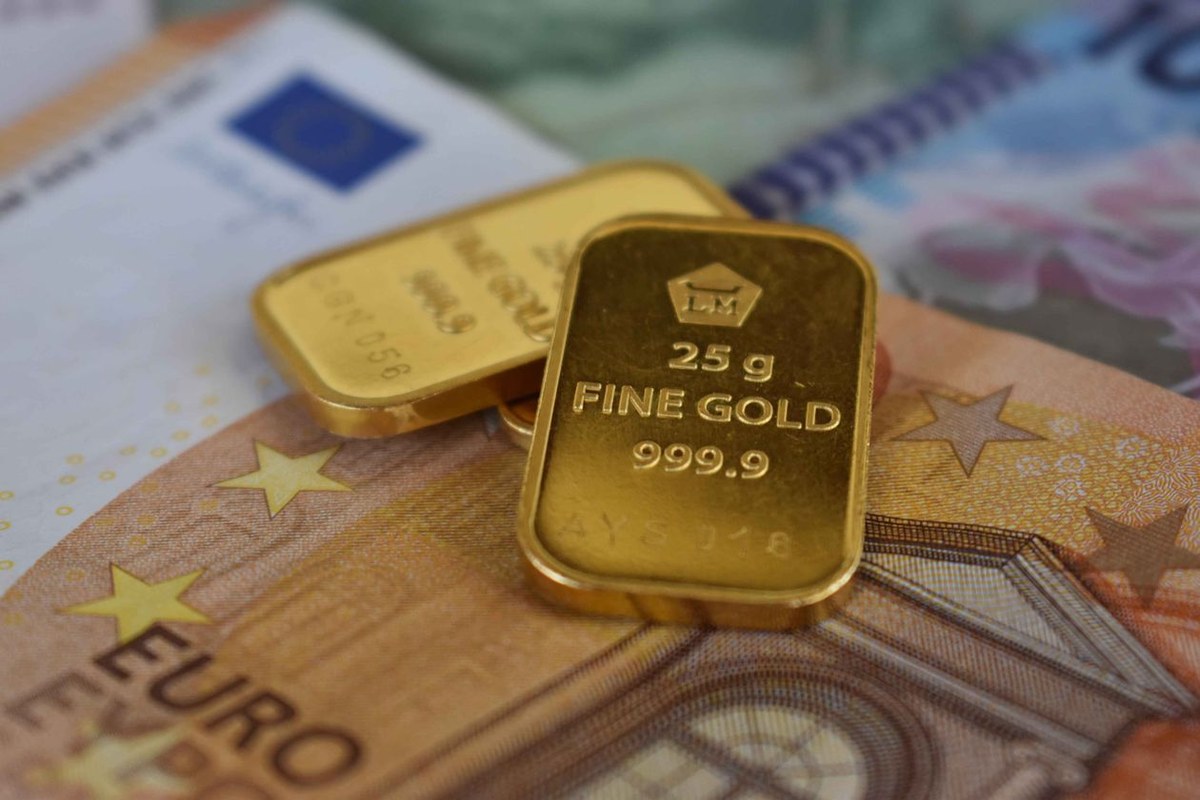
Two small gold bars stamped fine gold resting on Euro banknotes

Affluent banking is a stack, not a lounge photo

Malaysians who start looking at affluent banking often begin with the wrong artefact: a brochure of airport lounges, a gold bar on velvet, or a home-financing rate table printed in bold. Those artefacts matter later. First you need a clear stack: how day-to-day banking is supported, how surplus cash might sit in precious metal, and how a house purchase would be financed under an Islamic contract if that is your preference.

Two small gold bars stamped fine gold resting on Euro banknotes

Three lanes on one sheet. Answer your own questions before you argue with a relationship manager.

What “affluent” usually changes in practice

Affluent banking is not a personality label. It is a service layer: who you call when a transfer fails, how exceptions are handled, whether wealth and financing conversations sit with the same team, and which fees are waived only if balances stay above a threshold. Write those operational needs first. Travel weeks, multi-currency inflows, and family account structures create different pain points than a simple salary account.

When you scan public hubs that describe Al Rajhi Affluent, treat them like catalogues. Note relationship coverage hours, digital versus branch mix, and how product disclosure sheets are shared. Ignore lifestyle photography. A practical shortlist compares exception handling and fee clarity, not lounge photography.

Islamic affluent banking context in Malaysia also means asking how Shariah-compliant products are supervised and disclosed. Bank Negara’s Islamic finance framework sits behind licensed Islamic banks; your job as a customer is still to read the Product Disclosure Sheet for each facility, not to assume brand language equals contract detail.

Gold as a surplus holding, not a personality

Bank gold investment products attract people who want metal exposure without storing physical bars at home. The useful questions are boring: is ownership physical or constructive, how is allocation evidenced, what buy and sell spreads apply, and how quickly can you exit. Gold can sit beside cash for surplus you do not need next month. It is a poor substitute for emergency liquidity if spreads and delays are material.

Compare a bank bank gold investment pages page against a jewellery shop quote using the same purity and weight language. Ask for storage and ownership proof in writing. If you care about Shariah parameters, look for allocated gold and spot settlement language consistent with industry standards such as AAOIFI’s gold standard, and confirm the specific product’s Shariah notes rather than assuming the word “Islamic” covers every mechanic.

Hands presenting a residential loan application folder across a desk to a banker in a suit

Gold answers a surplus question. Home financing answers a housing question. Mixing the two into one emotional decision usually muddies both.

Islamic home financing: read the contract type

Home financing under Islamic banking uses trade, lease, or partnership-style contracts rather than a conventional interest loan label. That does not remove the need to understand monthly stretch, tenure, early settlement costs, and what happens if income dips. Ask which contract type applies, how profit rates are reviewed, and which documents the bank needs before offer.

Public pages that outline Islamic home financing help you scan features side by side. Bring your own numbers: take-home pay, existing commitments, and a buffer for rates that can reprice. Bank Negara’s consumer guides on home financing stress reading disclosure sheets and understanding your obligations before you sign; that habit beats chasing a headline rate.

If you want a neutral primer on how mortgage-style housing finance works in cash-flow terms (principal, interest or profit, and long tenure), Khan Academy’s introduction to mortgage loans is a clean educational walkthrough before you sit with any bank:

Related watch: Khan Academy explains mortgage loan mechanics in plain language, useful before you compare Islamic home financing disclosure sheets.

Read protections before comparing products

Eligible deposits at member banks sit under Malaysia’s deposit insurance system. PIDM deposit protection covers eligible deposits up to the stated limit per depositor per member bank, with separate treatment for conventional and Islamic deposits. Confirm each product’s eligibility. Cover does not protect investment losses on gold price moves or poor housing choices.

For housing finance literacy, Bank Negara’s consumer materials on Islamic banking consumer primers remain a stable map. Pair that with the Bank’s product transparency and disclosure rules so every shortlisted fee, rate, and obligation is readable on a disclosure sheet.

This month, keep the pass small. Map one service-layer need for affluent banking, price one gold exit scenario including spread, and draft a housing cash-flow buffer before you collect rate quotes. Affluent banking in Malaysia works better when the stack leads and the lounge photo follows.